The rise and collapse of Byju’s may look like another startup failure story. But in reality, it is also the story of a particular phase in Indian capitalism, when money was abundant, ambition was celebrated without restraint, and growth itself became a badge of success.
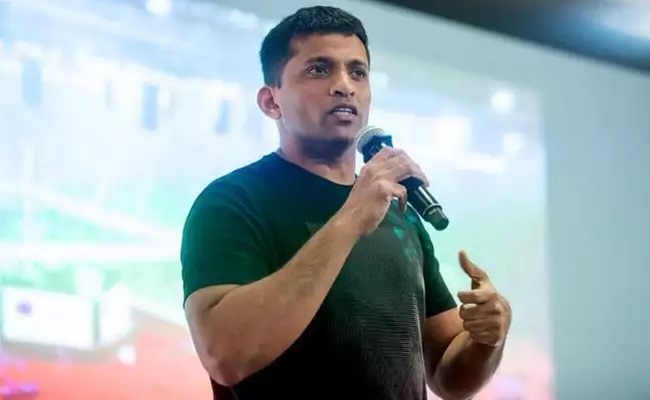
For years, Byju Raveendran represented aspirational India. The son of schoolteachers from Kerala built an education technology empire that once became India’s most valuable startup.
Investors praised him as a visionary. Parents trusted the brand for their children’s future. Politicians and business leaders projected Byju’s as proof that India could create global technology companies.
Today, the picture is completely different.
Byju’s, once valued at around $22 billion, has collapsed into bankruptcy and legal battles. Thousands of employees have lost their jobs. Investors and lenders are fighting in courts across India, Singapore and the United States.
In the latest blow, a Singapore court sentenced Raveendran to six months in jail for contempt over failure to comply with orders related to asset disclosure.
The irony is that Byju’s did not begin as a hollow idea. At its core, it had real talent and timing. Raveendran was known as a gifted teacher long before he became a billionaire entrepreneur.
He began by helping friends prepare for competitive exams and gradually built a strong following among students. His ability to explain complex problems in a simple and energetic way made him popular.
When smartphones and cheap internet spread rapidly across India, Byju’s was perfectly placed to grow. The learning app, launched in 2015, became popular with animated lessons, polished presentation and aspirational marketing.
For many students and parents, it looked like a modern alternative to traditional coaching centres.
Then came Covid-19.
The pandemic turned Byju’s into a giant. Schools were shut, children were stuck at home, and parents were desperate for online learning solutions.
Investors began treating edtech as the future of education. Byju’s user base surged, funding rounds became bigger, and valuations touched unbelievable levels.
But that success also sowed the seeds of its downfall.
During the boom, Byju’s expanded aggressively. It spent heavily on advertising, celebrity endorsements, cricket sponsorships, global campaigns and acquisitions.
It bought companies such as Aakash Educational Services, WhiteHat Jr, Great Learning, Epic and Tynker in quick succession. Every deal was projected as part of a larger plan to build a global education empire.
The problem was that Byju’s assumed pandemic-era growth would continue forever. But once schools reopened and normal life resumed, the demand for online learning slowed.
Parents became more cautious about spending. Students returned to classrooms. The future that Byju’s had prepared for did not arrive in the same form.
At the same time, the global startup mood changed. As interest rates rose and technology valuations fell, investors who once celebrated rapid growth started asking tough questions about profits, governance and financial discipline.
Byju’s was badly exposed. Its costs had ballooned. Its acquisitions were difficult to integrate. Its sales machinery was under pressure.
Parents began complaining about aggressive selling tactics and expensive subscription packages. Former employees spoke about unrealistic targets and intense pressure to close deals.
This damaged the company’s image badly. A brand that once looked like a trusted education platform began to be seen by many as a hard-selling business wrapped in the language of learning.
The company’s governance troubles deepened the crisis. Financial statements were delayed. Deloitte resigned as auditor. Board members stepped down. These developments raised serious questions about internal controls and transparency. Investors who had once backed the company enthusiastically began losing confidence.
The $1.2 billion term loan raised from foreign lenders became another major turning point. As the company’s financial condition worsened, disputes with lenders turned into legal battles.
Allegations around fund transfers, offshore structures and asset disclosures pushed the company further into crisis. Raveendran has repeatedly denied wrongdoing and maintained that some court matters are procedural rather than findings of fraud.
But by then, the damage to Byju’s credibility was severe.
One of the most striking moments came when Raveendran himself reportedly acknowledged that the company was “worth zero now.” For a startup once valued at $22 billion, that statement summed up the scale of destruction.
The Byju’s story is not just about one founder’s ambition. It is also about the role of global capital. Investors rewarded hypergrowth, pushed startups to expand fast, and celebrated large valuations. During the boom, spending heavily was seen as a sign of confidence. But when the cycle turned, the same strategy became a liability.
The biggest lesson from Byju’s is that valuation is not the same as value. A company can be worth billions on paper and still collapse if the business model, governance and cash flows are weak.
Another lesson is that extraordinary situations like the pandemic can distort judgement. Covid created temporary behaviour patterns, but Byju’s built its empire as though those patterns would last permanently.
Most importantly, Byju’s shows that ambition without discipline can destroy even a strong idea. The company was not brought down because it lacked vision. It collapsed because growth outran governance, spending outran sustainability, and confidence turned into excess.
Byju’s was once the symbol of India’s startup dream. Today, it stands as one of the sharpest warnings for the entire ecosystem: success can be more dangerous than failure when it removes all sense of restraint.